
Most insurance agencies grow the same way they did 15 years ago: referrals, a few purchased leads, a carrier-built website, and producers who are busy servicing the book they already have. Meanwhile the buyer has changed. In J.D. Power’s 2026 U.S. Insurance Shopping Study, customers collected an average of 3.5 auto quotes, the most in the study’s history, and 48% of new auto policies were bought digitally, up from 36% five years earlier.
Independent agencies still place 62% of U.S. property and casualty premium, according to the Big “I” 2026 Market Share Report, but only 39.5% of personal lines, where captive and direct carriers dominate. And most agencies compete on small budgets: the 2026 Agency Universe Study put the average agency marketing budget at $20,600, up from $14,300 in 2024. A plan is how a small budget gets pointed at the right households, the right lines and the renewals you should not be losing.
This guide covers the 2027 insurance agency marketing plan for independent P&C agencies and life, health and Medicare agents: why most agency marketing stalls, the quote and lead cost benchmarks that should set your spend, the rules to check before you call, text or advertise, and the 10 sections of the plan with worked examples. At the end, you can download our free fillable PDF workbook to build your own.
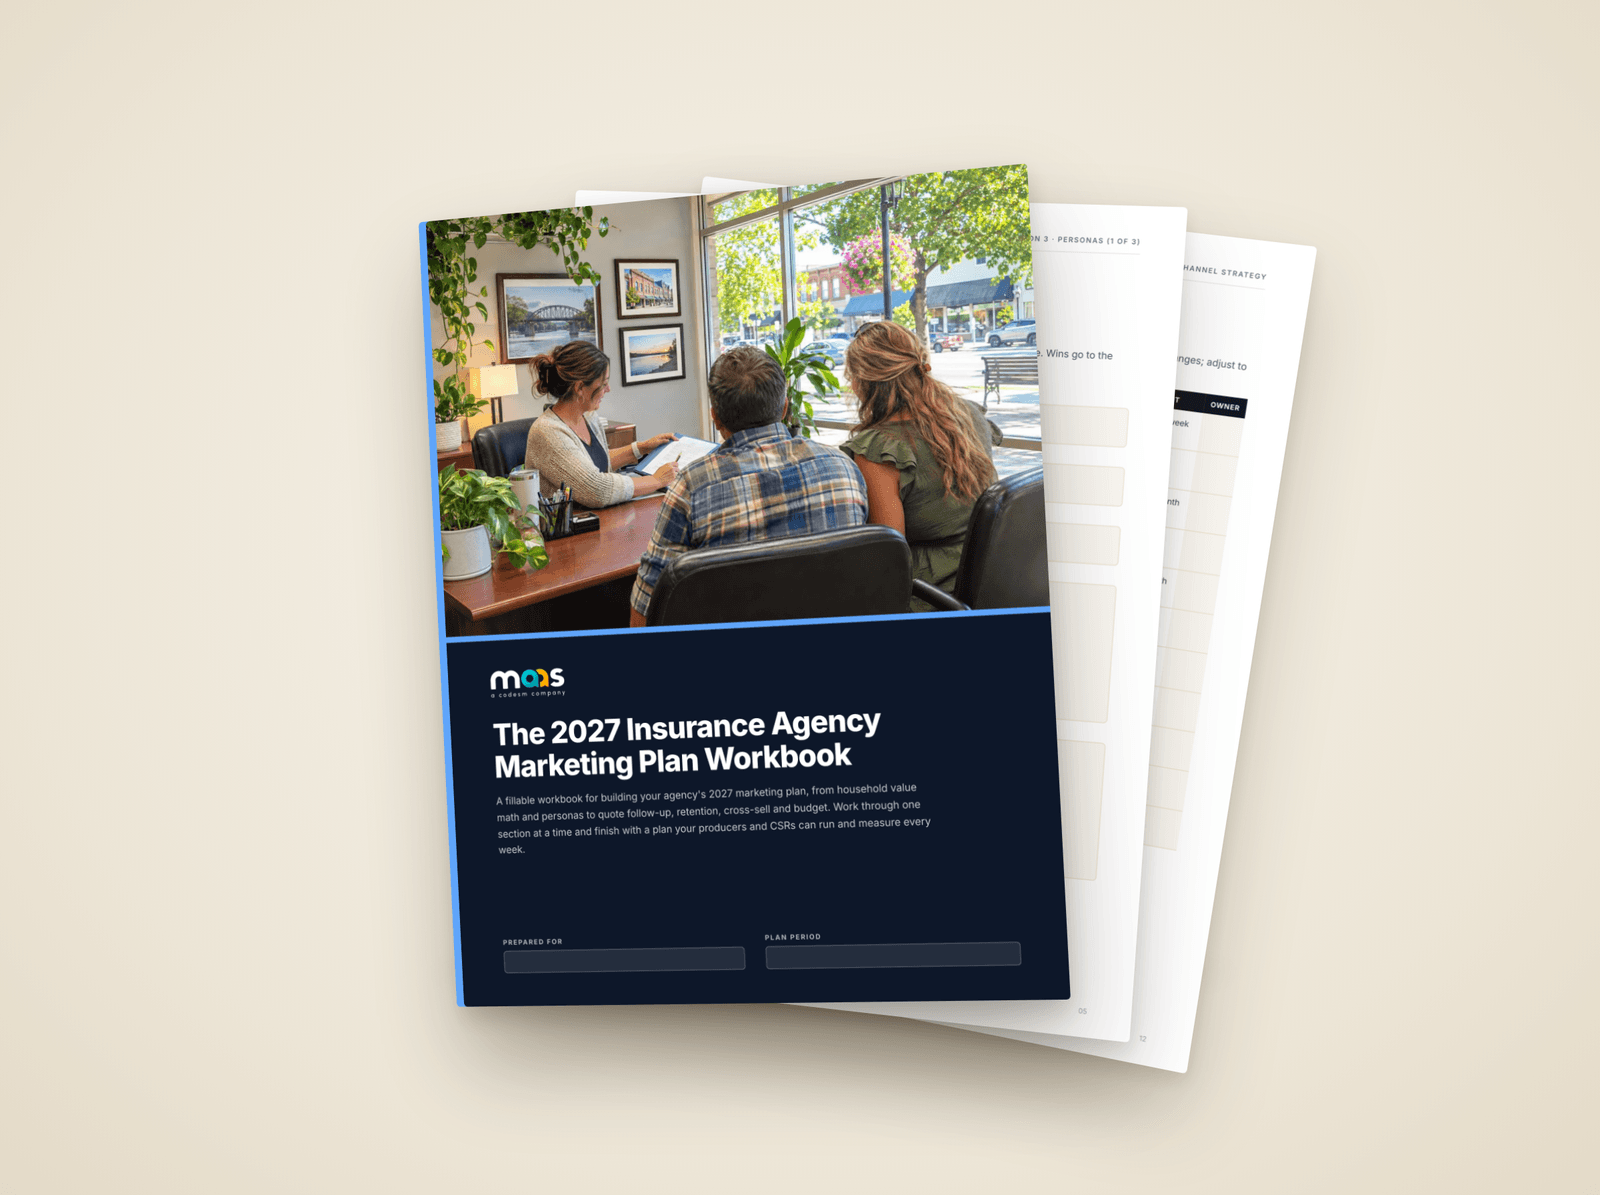
Click to download the free 2027 Insurance Agency Marketing Plan workbook (PDF)
Why most insurance agency marketing fails
The patterns are consistent across P&C, life and Medicare:
- Renting leads instead of building a pipeline. Shared leads go to several agents at once, so the agency that dials first wins and the rest pay for nothing. When the vendor budget stops, so does the growth.
- Quote and forget. A quote goes out, one follow-up call happens, and the household disappears. Nobody records the X-date (when the current policy renews), so nobody calls back when the price gets reconsidered.
- Monoline households. In the J.D. Power study, 45% of recent auto shoppers owned a homeowners policy, but only 20% received a homeowners quote while shopping for auto. Every one-policy client is a cross-sell you have not asked for and an easier household for a competitor to take.
- Renewals left to the carrier. A rate increase lands in the mail with no call from the agency. That letter is when clients start shopping.
- A referral program that is a sticker. “We appreciate your referrals” on an email signature is not a program. There’s no ask, no tracking and no thank-you.
- Consent gaps. Leads bought without a documented consent record, texts sent without written consent, Medicare outreach run like a P&C campaign. These are the gaps that turn into lawsuits and complaints.
- The same pitch as everyone else. “We shop multiple carriers for you” is true of every independent agency in town.
A plan fixes these by setting targets for new households, policies per household, retention and referral volume, and deciding in advance which channels will produce them.
The 2027 economics of insurance agency marketing
Start with household value, not cost per lead. A worked example: a household with auto and home that pays your agency $1,200 a year in commission and stays 6 years is worth about $7,200 in commission. Spending $400 to $600 to acquire that household is sound. Spending $150 on a monoline auto lead that never binds is not. Calculate the number for your own book by line before setting channel budgets.
Then compare channels on cost per bound household:
Cost per bound household = cost per lead ÷ (share of leads quoted × share of quotes bound)
Benchmarks to plan against:
- Search ads. LocaliQ’s 2026 search benchmarks put Finance and Insurance at a $3.39 average cost per click, a 9.83% click-through rate and a $74.44 average cost per lead, with a 2.64% conversion rate, the lowest of the 23 industries tracked. That category blends banking and insurance, and national head terms are crowded with carriers and comparison sites, so local, line-specific and commercial niche terms are where an agency competes best.
- Purchased leads. An ActiveProspect market review (September 2026) gives typical ranges of $10 to $45 for shared web leads, $45 to $120 for exclusive leads, $80 to $200+ for live transfers and $0.50 to $15 for aged leads, and notes that these are market estimates, not fixed pricing.
- Shopping behavior. In the J.D. Power study, the share of customers shopping for auto insurance fell from 57% to 53% year over year, still high by historical standards.
- Reviews. In BrightLocal’s 2026 survey, 97% of consumers read reviews for local businesses, 68% only use businesses rated four stars or higher, and 45% used ChatGPT or another AI tool for local recommendations, up from 6% a year earlier.
- Budget. There is no single public benchmark for agency marketing spend as a share of revenue. A common planning range is 2% to 5% of agency revenue, more in a growth year or a new market. Use the household value math above to check it.
| Channel | What it is good for | Benchmark or typical cost |
|---|---|---|
| Google Search Ads | Quote-intent searches by line and town | Finance and Insurance avg CPC $3.39, CPL $74.44 (LocaliQ 2026) |
| Google Local Services Ads | Pay-per-lead placement at the top of results | Insurance agency category in California and Florida only (Google) |
| Google Business Profile + local SEO | ”Insurance agency near me” and map pack | Free; staff or agency time |
| Purchased leads | Fast volume for producers with capacity | Shared $10 to $45, exclusive $45 to $120, live transfers $80 to $200+ (ActiveProspect) |
| Referral program | Best-retaining new households | Cost of the program; check state inducement rules |
| Retention and cross-sell automation | Policies per household, renewal saves | Planning range: $100 to $500/month for tools |
| Partners (realtors, lenders, dealers, CPAs) | Home, auto and business timing | Time and co-marketing |
| Meta Ads | Awareness, life and final expense, community, retargeting | Insurance lead costs not published; all-industry lead campaign CPL is $27.39 (LocaliQ 2026) |
| Organic social | Trust and visibility | Facebook used by 70% of agencies, Instagram 46%, LinkedIn 35% (Agency Universe Study) |
Rules to know before you market
This section is practical guidance, not legal advice. Rules vary by state and line, and carriers often add their own. Check with your compliance contact or counsel.
- State advertising and unfair trade practices rules. States prohibit misleading insurance advertising and misrepresentation, most through laws modeled on the NAIC Unfair Trade Practices Act. For life insurance and annuities, many states follow the NAIC advertising model regulation, which requires ads to be truthful and not misleading, including by implication. Practical rules: be licensed in every state you solicit in, name the insurer when you advertise a specific product, don’t promise savings you can’t support, and get carrier approval before using their names or logos.
- License numbers on materials. Some states require them. California has required license numbers on business cards, written quotes and print ads since 1997, and on emails since 2023, according to the California Department of Insurance. Check your state.
- TCPA: the one-to-one consent rule is gone, consent is not. The FCC’s rule requiring consumers to consent to each seller individually was vacated by the Eleventh Circuit on January 24, 2025 in Insurance Marketing Coalition v. FCC (Morrison Foerster summary), and the FCC later removed it from its rules. Prior express written consent is still required for autodialed or prerecorded telemarketing calls and texts to cell phones, Do Not Call rules still apply, and opt-outs must be honored within 10 business days. In fall 2026 the FCC also revised its consent revocation rules, replacing the delayed “revoke all” provision. Several states, including Florida and Oklahoma, have their own telemarketing laws. If you buy leads, get the consent record for every lead: the form, the disclosure text that names your agency, and a timestamp.
- Medicare (CMS rules). Medicare Advantage and Part D marketing has its own rulebook. Unsolicited phone calls, texts, voicemails, social media direct messages and door-to-door visits are prohibited; mail and email with an opt-out are allowed (42 CFR 422.2264). A Scope of Appointment is required before a personal marketing appointment and is valid for 12 months. For contract year 2027 materials (from October 1, 2026), CMS finalized changes that remove the 48-hour wait after a Scope of Appointment, allow marketing events directly after educational events with notice, require the third-party marketing organization disclaimer to be given verbally before plan benefits are discussed, and cut call recording retention from 10 to 6 years. The Annual Election Period (Medicare.gov calls it Open Enrollment) runs October 15 to December 7. Medicare Supplement plans are regulated by the states.
- Referrals and reviews. Many states restrict gifts or inducements tied to buying insurance or making referrals, so check your state before offering anything of value. The FTC’s reviews rule bans fake reviews, incentives conditioned on positive reviews and review suppression.
The 10-section insurance agency marketing plan framework
The workbook has a fillable page for each section.
1. Business snapshot
One page: lines written (personal, commercial, life, health, Medicare), carriers appointed, licensed states, households, policies, premium and commission revenue, policies per household, retention rate by line, producers and CSRs, languages spoken, and any niche (contractors, trucking, restaurants, farms, high-value homes). Then the one sentence on what makes you different. If it says “we shop multiple carriers”, keep working.
2. SWOT analysis
- Strengths: carrier depth, a commercial niche, bilingual staff, local reputation, claims advocacy, fast certificates.
- Weaknesses: monoline-heavy book, no renewal review process, thin reviews, dependence on one lead vendor, producers who don’t follow up.
- Opportunities: households with one policy, a growing community or industry in your territory, new carrier appetite, Local Services Ads if you’re in California or Florida, AI answers that don’t name a local agency yet.
- Threats: direct carriers with national budgets, captive agents nearby, carriers pulling back in catastrophe-prone areas, rate increases driving shopping, consent litigation.
3. Customer personas
Three personas cover most agency growth:
- The Rate Shopper. A renewal increase just arrived. Collects several quotes online and by phone, wants a number fast, and decides on price and how easy you make it. Win with speed, a bundle quote and a follow-up schedule tied to their X-date.
- The Life-Event Household. Just bought a home, added a teen driver, had a baby, got married, or is turning 65. Needs advice more than a price. Reached through realtors, lenders, dealers, content and well-timed outreach. Medicare-eligible clients belong here, under CMS rules.
- The Business Owner. A contractor, restaurant owner, trucker or professional who needs a package, certificates on demand and someone who understands their industry. Often referred by a CPA, a peer or a trade group, and worth more than several personal lines households.
For each, record: lines needed, trigger event, decision timeline, how they shop, objections, language preference, and the proof they need.
4. Competitive analysis
Pick five competitors, mixing captive agents nearby, independents and at least one direct carrier. For each: lines and niches promoted, Google rating and review count, quote experience (online form, call-only, instant quote), response speed on a test quote, language options, and content or social presence. Then ask ChatGPT and Google’s AI Mode for the best insurance agency in your town and note who gets named. Our AEO guide explains how to read and influence those answers.
5. Positioning statement
“For [who], [agency] is the [type of agency] that [difference] because [proof].”
Worked example (fictional agency): “For homeowners and small contractors around Tampa Bay, Gulfline Insurance Group is the independent agency that quotes home, auto and business coverage from 14 carriers in one conversation and re-shops any renewal that rises more than 10%, because our service team reviews every renewal 60 days before it is due.”
Every claim is specific and checkable, which is also what state advertising rules expect.
6. Goals and KPIs
Tie goals to households, policies and retention, not quote volume. Examples:
- Add 25 new households per month by Q4 2027, averaging 1.8 policies per new household.
- Raise book-wide policies per household from 1.4 to 1.6 within 12 months.
- Lift personal lines retention from 84% to 88% by contacting every renewal with a rate increase 45 days before it renews.
- Produce 40% of new households from owned channels (search, website, referrals, partners) instead of purchased leads by December 31.
- Reach 200 Google reviews averaging 4.8 or higher by year-end.
Weekly KPIs: quote requests by source, quotes issued, bind rate, new households, policies per household, renewal contacts made, retention, and referrals received.
7. Customer journey map
- Trigger. Renewal increase, life event, new business, claim frustration, turning 65.
- Research. Google, AI assistants, a friend, a realtor or CPA.
- Quote request. Form, call, text, walk-in, or a lead bought from a vendor.
- Quote delivery. Speed and clarity decide here.
- Follow-up. Plan several touches; many households need more than one conversation.
- Bind. Payment, documents, ID cards.
- Onboarding. A welcome call and a coverage review in the first 30 days.
- Mid-term check-in. Cross-sell review and life-event check.
- Renewal review. 45 to 60 days out, especially when rates rise.
- Advocacy. Reviews, referrals and partner introductions.
Most agencies are strong at steps 3 to 6 and nearly absent at 7 to 10, where retention and cross-sell are won.
8. Channel strategy
Investment figures are planning ranges for a small to mid-sized agency. Adjust to your market and lines.
| Channel | Role | Cadence | Typical investment |
|---|---|---|---|
| Google Business Profile | Local visibility, reviews, calls | Weekly posts, monthly photos | Free + 1 hr/week |
| Google Search Ads | Local and line-specific quote intent | Always on | $1,000 to $5,000/mo |
| Local Services Ads (CA and FL) | Pay-per-lead quote requests | Always on | $500 to $3,000/mo |
| Line and town landing pages + SEO | Owned quote demand | 2 to 4 pages/mo | $1,000 to $4,000/mo |
| Purchased leads | Volume for producers with capacity | Daily caps, weekly review | $500 to $5,000/mo |
| Referral program | Best new households | Ask at bind and at renewal | $100 to $500/mo |
| Partner program | Realtors, lenders, dealers, CPAs | Monthly touchpoints | Time + co-marketing |
| Renewal and cross-sell email/SMS | Retention, policies per household | Triggered + monthly | $100 to $500/mo tools |
| Meta Ads | Awareness, life lines, retargeting | Always on or seasonal | $300 to $2,000/mo |
| Organic social + video | Trust, community, coverage tips | 3 to 4 posts/week | Time |
| Community events and seminars | Local presence, Medicare education | Monthly or seasonal | $200 to $2,000/event |
Put call tracking on every channel so a phone call gets credited to its source (our dynamic number insertion explainer covers how).
9. Content strategy and calendar
Lead with answers to the questions clients ask CSRs every week, then short videos of your team answering them, then local risk and life-event content timed to the calendar. A workable cadence: 2 to 4 articles or pages a month, 3 to 4 social posts a week, one client newsletter a month, and a renewal-season campaign.
- Coverage explainers. “Does homeowners insurance cover a burst pipe?”
- Rate change explainers. Why premiums rose this year and what you can do about it.
- Local risk. Hurricane, hail, wildfire or flood prep timed to the season.
- Life-event checklists. New home, new teen driver, new baby, turning 65.
- Business owner guides. What a contractor needs before signing a commercial job.
- Claims help. What to do in the first hour after an accident.
- Medicare education. Enrollment periods and plan basics, with required disclaimers, no unsolicited outreach.
- Team and community. Your CSRs, local sponsorships, client milestones.
10. Budget allocation and measurement
Example split for an $8,000/month budget at an independent agency:
- Google Search Ads and Local Services Ads: $2,400 (30%)
- Purchased leads: $1,600 (20%)
- SEO and content: $1,200 (15%)
- Retention and cross-sell automation: $1,200 (15%)
- Referral and partner program: $800 (10%)
- Social and community: $400 (5%)
- Testing reserve: $400 (5%)
Measurement: a required lead source field in your agency management system or CRM (Applied Epic, AMS360, HawkSoft, EZLynx or similar), call tracking on every number, conversion tracking in Google Ads and GA4, consent records stored with every lead, and a monthly report of new households, policies and commission by source. The weekly dashboard uses the KPIs from section 6.
Common mistakes to avoid
- Buying leads without a speed plan. If shared leads aren’t called within minutes, stop buying them until they can be.
- Treating renewal as the carrier’s job. Review every renewal with a meaningful increase before the client sees the bill.
- One quote, one follow-up. Set a follow-up cadence and capture the X-date for every household that doesn’t bind.
- Never asking for the second policy. Quote home with auto, umbrella with home, and life at every life event.
- Running Medicare like P&C. No cold calls or texts, a Scope of Appointment before every appointment, and the disclaimer before benefits are discussed.
- Paying for referrals your state doesn’t allow. Check inducement rules first, then thank people in ways that comply.
- A carrier-template website. Build pages for your lines, towns and niches in your own voice.
Where to start if you’re starting from scratch
- Week 1. Sections 1, 3 and 5. Pull households, policies per household and retention by line from your management system. Three hours.
- Week 2. Claim and complete Google Business Profile, Apple Business Connect and Bing Places. Start asking every newly bound client for a review. Four hours.
- Week 3. Fix quote follow-up: a written cadence, X-date capture, a lead source field, and TCPA consent language on every form. Four hours.
- Week 4. Start a renewal review list for every policy renewing in the next 60 days with a rate increase. Four hours.
- Month 2. Launch Google Search Ads on local and line-specific terms, plus Local Services Ads if you’re eligible. Build landing pages for your top two lines.
- Month 3. Launch the referral and partner program and the weekly dashboard. Audit every lead vendor on cost per bound household and consent records.
- Quarter 2. Add content, cross-sell campaigns for monoline households, and a quarterly client newsletter. Medicare agents: plan AEP materials by September.
- Year 1. Review new households, retention and policies per household by source, then reallocate.
FAQ
What are some effective marketing ideas for an insurance agency? A complete Google Business Profile with steady reviews, local landing pages for each line, a written quote follow-up cadence, renewal reviews before rates hit, a referral and partner program, and cross-sell campaigns to monoline households. Owned channels compound; purchased leads stop when spending stops.
How much should an insurance agency spend on marketing? The 2026 Agency Universe Study put the average agency marketing budget at $20,600. A common planning range is 2% to 5% of agency revenue, more in a growth year. Check it against what a new household is worth to you.
Should insurance agents buy leads? Only with the capacity to call within minutes, a follow-up cadence, and a documented consent record for every lead. Judge vendors on cost per bound household, not price per lead, and keep building owned channels.
Is the TCPA one-to-one consent rule still in effect? No. The Eleventh Circuit vacated it in January 2025 and the FCC removed it. Prior express written consent is still required for autodialed or prerecorded marketing calls and texts to cell phones, and opt-outs must be honored.
What are the 7 P’s of the insurance marketing mix? Product, price, place, promotion, people, process and physical evidence. For an agency, people (producers and CSRs) and process (quote speed, follow-up, renewal reviews) are usually where the plan has the most room to improve.
Download the full template
The workbook is a fillable PDF companion to this guide. Inside:
- How to use the workbook
- Business snapshot
- SWOT analysis
- Three persona templates (Rate Shopper, Life-Event Household, Business Owner)
- Competitive analysis matrix (5 competitors)
- Brand positioning canvas with a worked example
- Goals and KPI tracker with a monthly check-in
- Customer journey map (10 stages)
- Channel strategy matrix
- Content framework and 30-day content calendar
- Budget allocation worksheet with an example split
- Tech stack checklist and weekly measurement dashboard
- 12-month action plan
- Common mistakes checklist and quick-start plan
Download the 2027 Insurance Agency Marketing Plan workbook (PDF)
If you’d rather have a team run this for you, from quote campaigns and landing pages to renewal nurtures, review generation and weekly reporting by bound household, that is the work the insurance marketing team at MaaS by CodeSM does every day. Get in touch and we’ll review where your agency stands and map the plan. For more on the review side, see how to ask for (and get) more good reviews.
Share this article